The wars in Ukraine and Iran are catastrophic failures of political judgment. Their human cost alone should have forced a different course. Their energy consequences now give the world another urgent reason to demand one.
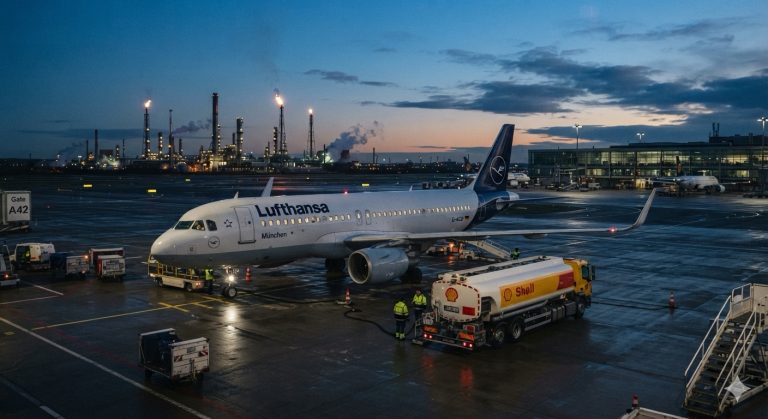
The danger reaches far beyond the battlefield. It reaches the fuel that keeps aircraft flying, trucks delivering, farms working and homes warm. As the Northern Hemisphere approaches winter 2026–27, kerosene and diesel deserve far more attention than political declarations of strength or success.
Larry C. Johnson’s Warning: The Crisis Beyond Crude Oil
Larry C. Johnson has been drawing attention to precisely this vulnerability. In his 18 September Sonar21 article, The Squeeze Reaches the Runway: The Distillate War Is Now Cutting Flights, he argues that the critical weakness lies in the chain that converts crude oil into usable fuel and delivers it where it is needed.
His warning is concise:
“A ceasefire can cut the crude bill. It cannot instantly refill the middle of the barrel.”
— Larry C. Johnson, Sonar21, 18 September 2026.
That distinction matters. A lower headline oil price does not guarantee affordable kerosene at an airport or diesel at a distribution terminal.
Kerosene Makes the Crisis Visible
Why Available Oil Does Not Guarantee Available Fuel
Commercial aviation relies predominantly on kerosene-based jet fuel. Alongside diesel, it belongs to the family of middle distillates whose production depends on available crude, functioning refineries and the equipment those refineries operate.
There is flexibility: light crude can produce both fuels, and processes such as hydrocracking can increase their output. But that flexibility has physical limits. Replacing disrupted supplies requires suitable feedstock, processing capacity and transport—not merely a different supplier on paper.
The US Energy Information Administration explains these production relationships in its material on refinery inputs and outputs and hydrocracking.
The Pressure on Aviation and Tourism
The price pressure is measurable. When consulted on 19 September 2026, IATA’s Jet Fuel Price Monitor reported a global average refinery price of $181.46 a barrel, up 6.1% in one week. This is a wholesale benchmark; an airline’s actual bill also depends on its contracts and delivery arrangements. Nevertheless, it is a clear indicator of the pressure on aviation. Source: IATA.
Johnson describes airlines reducing schedules as fuel costs undermine the economics of particular flights. He also acknowledges that some cancellations reflect weaker demand, so every withdrawn route cannot be attributed to a fuel shortage. His broader warning remains compelling: sustained kerosene inflation threatens connectivity even where people still want to travel. Source: Sonar21.
For economies dependent on tourism, the potential consequences extend beyond the airline balance sheet. Fewer affordable flights can mean fewer visitors, lost bookings and lower incomes for hotels, guides, restaurants and small businesses.
Ukraine and Iran: Two Conflicts, Compounding Damage
The Energy Consequences of the Ukraine War
The energy consequences of the Ukraine war began well before this autumn. Russia’s invasion in 2022, its reductions in gas deliveries, and Western sanctions and efforts to replace Russian supplies disrupted established energy trade. Europe’s search for alternative gas also transmitted higher costs to buyers elsewhere. Source: IEA, background on the 2022 energy crisis.
The current damage increasingly concerns refined fuels. In an analysis published on 17 September 2026, the International Energy Agency reports that intensified Ukrainian attacks on Russian refineries have reduced processing and diesel production. It explicitly identifies the loss of Russian supplies as an additional strain on markets already suffering from reduced Middle Eastern exports. Source: IEA.
The Combined Loss of Russian and Gulf Supplies
The September IEA Oil Market Report makes the connection concrete: combined net diesel and gasoil exports from the Gulf and Russia were approximately 1.6 million barrels a day lower in August than in February.
It also reports a 507-million-barrel decline in observed global oil inventories since February. Those inventories include more than kerosene and diesel, but their depletion shows how heavily the system has relied on stored supplies. Source: IEA, September 2026.
The political conclusion I draw is straightforward: pursuing military outcomes while allowing the energy infrastructure of major producing regions to deteriorate is an extraordinary gamble with civilian livelihoods.
Recognising that danger does not require pretending that both wars have identical origins or that every participant bears identical responsibility. It requires recognising that their economic consequences reinforce each other.
Karl Miller’s Warning: Fuel Must Actually Arrive
Delivery and Financing Can Become Breaking Points
In his 17 September article, Johnson summarises a private assessment by energy-sector specialist Karl Miller, dated 16 September and titled Judgment Day Has Arrived.
As Johnson presents it, Miller’s central concern is whether usable fuel can reach the buyer in time. National inventories offer limited reassurance to an airport facing a missed delivery. High prices and longer transport times also increase financing requirements, potentially excluding weaker buyers before supplies disappear altogether.
Scenarios Must Be Distinguished from Measured Shortages
There is an essential qualification: Johnson says Miller’s numerical stress cases are illustrative scenarios, not measured global deficits. The underlying private report was not available for independent inspection here. Miller’s analysis is therefore cited through Johnson’s published account.
This distinction strengthens the warning. We should judge it by observable deliveries, inventories and prices, rather than turn every scenario into a prediction.
Winter 2026–27: A Serious Risk, Not a Predetermined Outcome
What the Official Forecasts Say
The EIA’s September outlook forecasts US distillate inventories falling below 100 million barrels in September and remaining below their five-year seasonal low through much of 2027. It also anticipates gradual improvement in Middle Eastern production.
Its forecast was completed on 3 September, so it does not incorporate subsequent events. Source: EIA.
These findings support concern about prolonged fuel stress. They do not establish that every country will experience shortages, or that gas, electricity and aviation fuel will fail together.
How the Crisis Could Reach Households and Businesses
The risk is that winter heating requirements collide with persistent transport demand and inadequate replenishment. The consequences could include more expensive journeys, reduced services, pressure on food distribution and businesses cutting activity because operating costs become unaffordable.
The severity will depend on weather, repairs, trade flows and diplomatic progress.
Johnson’s prediction of economic collapse is more categorical than the official forecasts. It should be understood as his warning about where continued escalation could lead, rather than a settled description of the future.
But uncertainty is no excuse for complacency. A crisis does not have to become a universal blackout to destroy livelihoods.
The Political Failure—and the Bill Still to Come
The strategic mistake is to keep treating the functioning of the civilian economy as an acceptable wager. Diplomacy, protection of energy infrastructure and reliable supply arrangements must become urgent priorities.
The wars in Ukraine and Iran have already imposed immense suffering. Allowing their energy consequences to deepen through another winter would compound that failure.
The people paying for these wars are not confined to the countries fighting them. This winter, the bill could arrive through the airport, the supermarket and the heating tank.
Karl Miller’s private assessment is referenced through Johnson’s published summary. Institutional figures are attributed to their respective sources, and forecasts remain forecasts.